Articles to keep you learning
If there is one question I have been asked more than any other over the past year, it is this: “Where do you think interest rates are going?” My honest answer is probably not as satisfying as people would like. I don't know. And I say that as someone who has spent years working in the mortgage business, watching rate cycles, talking to lenders every day and helping Canadians navigate everything from their first mortgage to renewals, refinances and investment properties. I am not an economist, and I certainly don't pretend to know where interest rates will be 12 months from now. What I can do is watch the numbers, listen to what the economists are saying, understand how the mortgage market is reacting and, perhaps most importantly, look at what I am seeing in the real world with actual borrowers. And right now, I think homeowners should be prepared for a period where rates may not move nearly as dramatically as they did a few years ago but they also may not give us the steady decline that some borrowers have been hoping for. So, where are rates headed? As of September 2026, the Bank of Canada's overnight rate is 2.25 per cent. The Bank has held that rate since late 2025. The interesting part is what happens next. Recent forecasts are far from unanimous. Some major financial institutions expect the Bank to remain at 2.25 per cent for an extended period, while others are forecasting gradual increases during 2027. Depending on the institution and the timing of its forecast, some projections have the overnight rate reaching somewhere around 2.50 to 3.25 per cent over the course of 2027. There are good arguments on both sides. The Bank of Canada has been dealing with an economy that has shown weakness, while inflation has generally been moving toward its target. At the same time, there are renewed inflation risks from energy prices and ongoing trade uncertainty. That leaves us in an interesting position. I wouldn't build a household budget around the assumption that rates are going significantly lower. But I also wouldn't panic and assume we are heading back to the five, six or seven per cent mortgage rates that Canadians experienced during the last major rate shock. My expectation (and this is simply my view, not an economic forecast) is that the next year could be more about stability and modest movements than dramatic rate changes. There is a reasonable possibility of some increases, particularly if inflation remains stubborn, but there are also economic conditions that could keep the Bank cautious. In other words, I think borrowers should plan for the possibility of higher rates without making the mistake of assuming they are inevitable. This is where variable mortgages get interesting I've had a lot of conversations with clients who chose—or needed to choose—a variable-rate mortgage. There is an important distinction here. Some borrowers choose variable because they believe rates will fall. Others choose variable because it is the only way the numbers work. Those are very different situations. The second group is the one I worry about more. I've had clients who qualify for a purchase at a particular price only because the variable mortgage gives them a payment that fits within their monthly budget. There isn't a lot of room between what they make, what the lender will approve and what the household actually needs to spend each month. For those borrowers, a quarter-point increase isn't just an interesting economic headline. It affects the family budget. And that's why I don't think the right question after your mortgage closes is simply, “What is the rate today?” The better question is: “How much room do I have if the rate goes up?” If you're in a variable mortgage, give yourself some breathing room If you have just finalized a variable mortgage and your budget is already tight, I would suggest doing something very simple. Don't immediately spend the difference between your mortgage payment and your maximum affordable payment. If your current mortgage payment is $3,000 but you know you could manage $3,300 if you had to, consider pretending the payment is already $3,300. Put that extra $300 into savings every month. There are a few advantages to doing this. First, you build an emergency fund. Second, if rates increase, you already have some room in your budget. Third, if rates remain where they are, you have accumulated money that can potentially be used toward your mortgage principal, an upcoming expense or another financial goal. It also changes the psychology of the situation. Instead of waiting for a rate increase and then scrambling to find another $200 or $300 a month, you've already built that money into your household routine. Don't wait until the renewal date to have the conversation Another mistake I see is borrowers waiting until three weeks before their mortgage renewal to start thinking about what they want to do. That's too late. If you have a variable mortgage, I suggest reviewing your situation periodically, particularly if your household income, expenses or debt have changed. And if rates start moving higher, don't immediately assume the answer is to break your mortgage and lock into a fixed rate. There are costs and trade-offs involved. Depending on the mortgage, there may be penalties to break it. Fixed rates can also move independently of the Bank of Canada's overnight rate because they are influenced by the bond market. Sometimes the best move is to stay variable. Sometimes converting to a fixed mortgage makes sense. Sometimes increasing your payment is the better answer. Sometimes the right answer is simply to do nothing and wait. That is where having an actual conversation with your mortgage professional can be valuable. Watch your payment—not just the interest rate This is particularly important for people with variable mortgages. Depending on the mortgage product, a change in the interest rate can affect the payment differently. Some variable mortgages have payments that change as the lender's prime rate changes. Others may keep the payment relatively stable for a period of time, with more of the payment going toward interest and less toward principal. Borrowers need to understand which type they have. I would encourage every variable-rate borrower to know three numbers: Your current payment. Your current interest rate. The rate at which your mortgage payment or amortization becomes a problem. That third number is the one that tends to get overlooked. What if rates start increasing? If we start seeing a series of rate increases, my advice would be to avoid making decisions based on fear. A quarter-point increase is worth paying attention to. It isn't necessarily a reason to panic. If rates rise, I'd suggest doing the following: Review your household budget and identify discretionary spending that can be reduced temporarily. Keep building or maintaining an emergency fund. Consider increasing your mortgage payment voluntarily if your budget allows. Make lump-sum payments when you have the ability and your mortgage allows them. Talk to your mortgage broker before breaking a mortgage or locking into another product. Find out what fixed-rate options are actually available rather than assuming today's advertised rate is the only option. Revisit your mortgage if your financial circumstances have changed significantly. Don't make a long-term decision based solely on what you think the Bank of Canada will do at its next meeting. The last point is important. Nobody knows exactly what the Bank of Canada is going to do next. I've been around long enough to see plenty of confident predictions turn out to be wrong. If you are reading this and thinking, “That's great advice, but I barely qualified for my mortgage in the first place,” then I would approach things a little differently. Your first priority should be cash flow. Don't take on a mortgage payment that leaves you with nothing left at the end of the month. And once your mortgage closes, don't immediately assume that because the lender approved you, you have to spend every dollar of your available income. Give yourself a buffer. If you can put $200, $300 or $500 a month into a separate savings account, do it. Call it your “mortgage rate fund.” If rates rise, that money is there. If rates don't rise, you've created a useful savings account. And if rates eventually fall, you've still benefited from developing the habit of living below your maximum mortgage payment. That is much more sustainable than trying to predict the Bank of Canada correctly every six weeks. The biggest mistake is betting your household on a forecast. The mortgage industry loves forecasts. So do newspapers. So do economists, investors and, apparently, people like me who spend far too much time talking about interest rates. But forecasts are forecasts. They change. The Bank of Canada's own outlook acknowledges significant uncertainty, and recent economic developments including inflation, energy prices and trade conditions can change the interest-rate picture surprisingly quickly. So rather than asking me, “Do you think rates will be lower next year?” I'd rather have a client ask: “What happens to me if they're not?” That's a much better mortgage question. If you can comfortably afford your mortgage at today's rate and have some room in your budget, you're in a much better position to ride out whatever happens next. If you're stretched to the limit, I'd rather see you address that now than wait for a rate increase to force the conversation. And if you're considering a variable mortgage because it's the only way the purchase works, that's not necessarily a bad decision but it should be a decision you make with your eyes open. Know what happens if rates rise by 0.25 per cent. Know what happens if they rise by 0.50 per cent. Know what happens if they don't move at all. And, perhaps most importantly, have a plan for each scenario. Because after years in the mortgage business, one thing I've learned is that the people who tend to sleep best at night aren't necessarily the ones who picked the perfect mortgage. They're the ones who gave themselves enough room that they didn't need to. Note: This column reflects my perspective as a mortgage broker and is intended for general information only. I am not an economist or financial adviser, and interest-rate forecasts are inherently uncertain. Mortgage decisions should be based on an individual's circumstances, financial position and risk tolerance.
One of the more interesting conversations I have with clients isn't always about which mortgage rate they should take. Sometimes, the bigger question is: How much money should you actually put into your home? For many Canadians, the answer seems obvious. If you have the money, put it into the house. A larger down payment means a smaller mortgage, lower monthly payments and less interest paid over time. And there is certainly a lot to like about that approach. But what if you also have a substantial investment portfolio that has been performing very well? Is it always better to take money out of your investments and put it into your home? Not necessarily. A real-world example I recently had a client situation that illustrates this perfectly. The client purchased a home worth $900,000. He had enough available capital to put down 50 per cent, or $450,000. Instead, he chose to put down 20 per cent — $180,000 — and keep the other $270,000 invested. His reasoning was straightforward. His investment portfolio had averaged approximately 23 per cent annually over the previous three years, and he believed the potential long-term growth of keeping that money invested outweighed the benefit of putting another $270,000 into his home. At first glance, the numbers certainly make the decision interesting. But before anyone sees a 23 per cent return and thinks this is an easy decision, there is an important point to make. A 23 per cent average annual return is an exceptional historical result. It is not a guaranteed return, nor should anyone assume that a portfolio will continue producing 23 per cent year after year. Many investments and portfolios don't come close to that level of performance. That's what makes this decision so personal. The case for putting more money into the house is that there is something very satisfying about paying down a mortgage. When you put an additional dollar into your home, you are reducing the amount you owe and, in turn, the amount of interest you will pay. Unlike an investment return, the savings from paying down your mortgage are much more predictable. Let's say, for example, your mortgage rate is 4 per cent. Putting $100,000 against that mortgage effectively saves you the interest you would otherwise have paid on that $100,000, subject to how your mortgage is structured and how long you keep the debt. A larger down payment can also mean: A smaller mortgage balance. Lower monthly payments. Less interest paid over time. More equity in your home from day one. Less financial stress for people who prefer carrying less debt. For someone who values certainty, paying down debt can be an excellent financial strategy. There is also an important Canadian mortgage consideration: 20 per cent is a significant threshold. Generally, a down payment of less than 20 per cent requires mortgage loan insurance, while 20 per cent or more allows you to obtain a conventional mortgage. Once you've reached that 20 per cent threshold, however, the conversation can become much more interesting. The biggest advantage of keeping some money invested is liquidity and diversification. Your home is an asset, but the money tied up in your home isn't particularly easy to access. If you put an additional $270,000 into the property, that money becomes home equity. If you leave that $270,000 invested, it remains part of your financial portfolio and may continue to grow. Depending on the investments, you may also have the ability to access some of that capital if circumstances change. In my client's example, $270,000 is a significant amount of money. If that money were to earn 23 per cent in a particular year, the gain would be approximately $62,100. Compare that with a 4 per cent mortgage. A 4 per cent cost of borrowing on $270,000 would represent approximately $10,800 of interest in the first year, before considering how the mortgage balance changes through payments. On the surface, that makes keeping the money invested look very attractive. But there is an important catch. Investment returns are not guaranteed. The mortgage rate represents a cost you can calculate. Your investment return is uncertain. Your portfolio could earn 23 per cent. It could earn 5 per cent. It could earn nothing. It could also lose money. That's the trade-off. Don't confuse a great three years with a guaranteed future This is probably the most important point I'd make to anyone considering this strategy. Past investment performance is not a promise of future performance. My client's portfolio averaging approximately 23 per cent over three years is impressive. But three years is a relatively short period when you're making a decision that could affect your finances for decades. Markets go through good periods and bad periods. A portfolio that has performed exceptionally well can experience a significant downturn. And unlike your mortgage payment, you can't count on your investment portfolio producing a specific return next year. That's why I would never tell a client that keeping their money invested is automatically better than paying down their mortgage. It isn't. There is also something to be said for peace of mind. Personal finance isn't just about spreadsheets. Two people can look at exactly the same numbers and make completely different decisions — and both can be making perfectly reasonable choices. One person may look at a $450,000 mortgage and think, "I want that debt as small as possible." Another may look at the same mortgage and say, "I'm comfortable carrying the debt because I want to keep my investments working for me." Neither person is necessarily wrong. Your income, job stability, age, investment risk tolerance, tax situation, other debts, retirement plans and overall financial picture all matter. And perhaps most importantly, your ability to tolerate risk matters. If seeing your investment portfolio fall 25 per cent would cause you to panic and sell everything, keeping a large amount invested simply because it has performed well recently may not be the right strategy for you. There is a middle ground It doesn't have to be an all-or-nothing decision. You don't necessarily have to put either 20 per cent or 50 per cent down. You might choose 25, 30 or 35 per cent, for example, while keeping some money invested. That can provide a balance between reducing mortgage debt and maintaining investment exposure. The right answer depends on the individual. For some people, the predictable benefit of reducing debt will be more valuable than the potential investment gains. For others, particularly those with strong cash flow, a long investment horizon and a diversified portfolio, maintaining investments while carrying a larger mortgage may make more sense. So, what's the right answer? As a mortgage broker, my job is to help clients understand the mortgage side of the equation. I can show them how different down payments affect their mortgage amount, payments and borrowing costs. But I don't believe there is one universal answer to the question of whether you should put 20 per cent down or 50 per cent down. The client with the $900,000 home made a decision that made sense for his particular circumstances. He chose to put $180,000 down, keep approximately $270,000 invested and accept the investment risk that came with that decision. His portfolio's approximately 23 per cent average return over the previous three years certainly makes the decision look good in hindsight. But hindsight is a wonderful thing. None of us knows what the next three years will look like. The lesson isn't that you should keep your money invested because investments can outperform your mortgage. The lesson is that your home equity and your investment portfolio are two different pieces of your overall financial picture and deciding how much to allocate to each deserves careful consideration. A larger down payment can provide certainty, lower debt and peace of mind. Keeping money invested can provide liquidity, diversification and the potential for greater long-term growth but with substantially more uncertainty. There is no magic percentage that works for everyone. Disclosure: I am a mortgage broker, not a financial planner or investment advisor. The investment example above is based on an individual client's historical experience and should not be interpreted as a forecast or recommendation. Investment returns vary, and not all investments or portfolios perform anywhere near this level. Before deciding whether to put more money into your home or keep it invested, you should speak with your own qualified financial advisor or financial planner to determine whether the strategy makes sense for your individual circumstances. Sometimes the best mortgage decision isn't simply about getting the smallest mortgage possible. It's about finding the balance between debt, investments, risk and peace of mind that works for you.
After years in the mortgage business, one of the questions I hear most often from homeowners is, “How can I get this mortgage paid off sooner?” It’s a good question. A mortgage may be considered “good debt” because it helps us buy a home, but that doesn’t mean anyone wants to be making mortgage payments for the full 25 or 30 years if they can avoid it. The good news is that most Canadian mortgages give homeowners several ways to accelerate their payments and reduce the amount of interest they pay over the life of the mortgage. The key is understanding how your mortgage works and making use of the prepayment privileges that are already built into your contract. Start by understanding amortization First, it’s important to distinguish between your mortgage term and your amortization. Your term is the length of time your current mortgage agreement and interest rate are in place. Five years is a common mortgage term. Your amortization is the total length of time it would take to pay off the mortgage if you simply made the required payments and did nothing extra. A 25-year amortization is very common. You don't have to wait 25 years to become mortgage-free. There are several strategies that can shorten that timeline considerably. Increase your regular payments The simplest strategy is often the one that gets overlooked: increase your regular payment. If your mortgage payment is $2,500 and you increase it to $2,750, that additional $250 is going toward your mortgage balance. As the principal comes down, you pay less interest over time. Most Canadian banks offer some form of annual payment increase privilege on closed mortgages. A common privilege is the ability to increase your regular payment by 10 per cent, although some lenders offer more. That means a homeowner doesn't necessarily have to wait for a large windfall to make a difference. Increasing the payment by a manageable amount can gradually have a significant impact. Make a lump-sum payment Another popular option is a lump-sum prepayment. Perhaps you receive a work bonus, a tax refund, an inheritance or proceeds from the sale of an investment. Instead of spending all of it, you can put some of that money directly against your mortgage principal. Many Canadian lenders allow homeowners to make an annual lump-sum payment without a penalty. A common privilege is 10 per cent of the original mortgage amount, although some lenders allow 15, 20 or even more. For example, on a $500,000 mortgage, a 10 per cent annual prepayment privilege could allow you to put $50,000 directly against the mortgage without a prepayment penalty. That's a pretty powerful tool. Of course, every mortgage contract is different, so it's important to check the exact privilege before making a large payment. Take advantage of payment frequency This brings us to one of the most common questions I get: What's the difference between bi-weekly and accelerated bi-weekly payments? The difference is bigger than many people realize. Let's use a $500,000 mortgage at 3.99 per cent with a 25-year amortization as an example. The monthly payment would be approximately $2,630. A regular bi-weekly payment takes that monthly payment, multiplies it by 12 and divides it by 26. That works out to approximately $1,214 every two weeks. Because there are 26 bi-weekly payments in a year, you're essentially making the equivalent of 12 monthly payments over the course of the year. Now let's look at accelerated bi-weekly payments. Instead of taking the monthly payment and converting it to a bi-weekly payment, the lender simply divides the monthly payment in half. $2,630 divided by two gives us an accelerated bi-weekly payment of approximately $1,315. Here's where the difference becomes important. You're making 26 payments of $1,315, which works out to approximately $34,190 per year. With regular bi-weekly payments, you're making 26 payments of approximately $1,214, or about $31,564 per year. That's a difference of roughly $2,630 a year — essentially one extra monthly mortgage payment. And that extra payment goes directly toward getting the mortgage paid down faster. The numbers at a glance
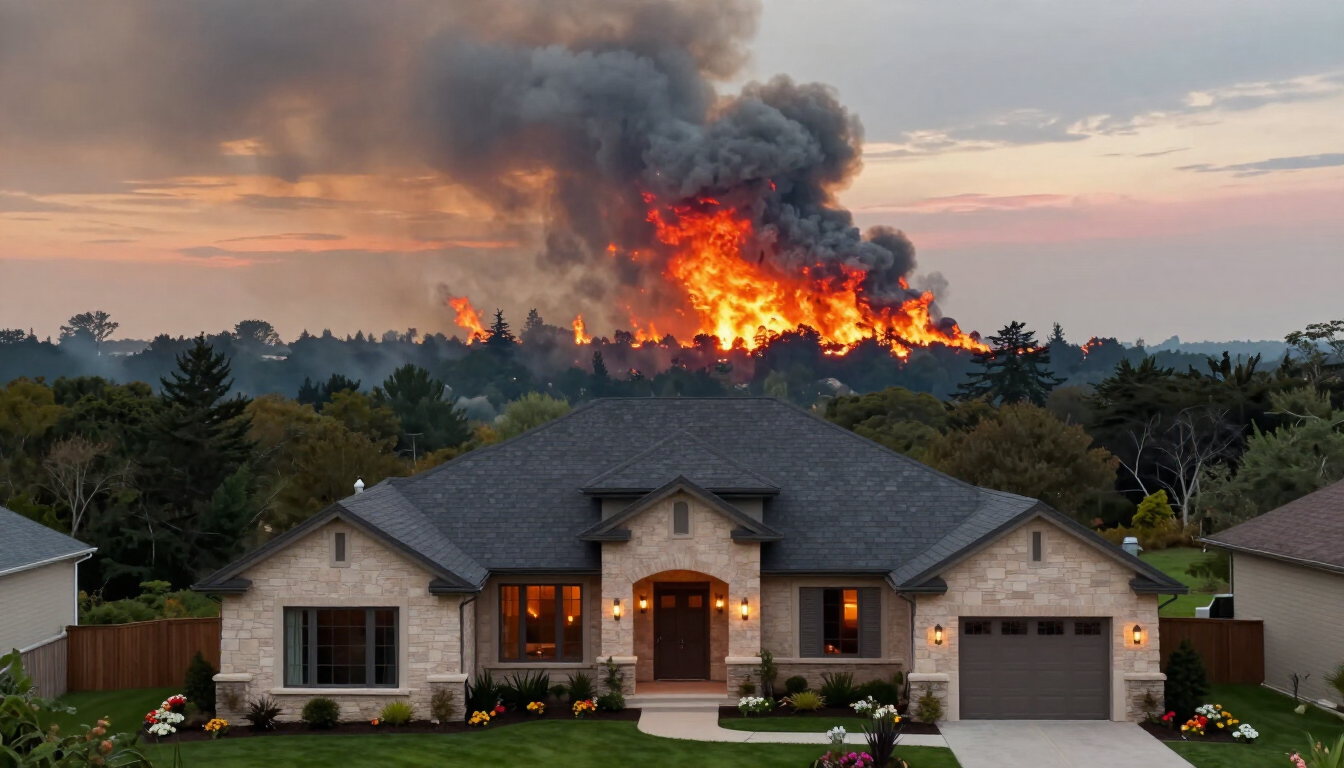
For many Canadians, buying a home is one of life's most exciting milestones. You've found the perfect property, negotiated an accepted offer, arranged financing, and started picturing where the furniture will go. Then, almost overnight, Mother Nature throws a curveball. A wildfire starts nearby. As someone who has spent many years helping Canadians navigate home financing, I've seen firsthand how quickly a wildfire can change what seemed like a straightforward transaction. The good news is that many purchases still close successfully—but it's important to understand how these situations can affect everyone involved. One of the most important concepts in a real estate contract is something called force majeure . While the exact wording varies depending on the contract, a force majeure clause generally recognizes that extraordinary events beyond anyone's control—such as natural disasters—may temporarily prevent one or more parties from fulfilling their contractual obligations. If evacuation orders are issued, government offices close, roads become inaccessible, or lawyers, lenders, appraisers, or buyers simply cannot complete the necessary steps to transfer ownership, a force majeure clause may allow the closing date to be postponed until those circumstances have passed. It doesn't automatically cancel the sale, but it can provide valuable flexibility during an unpredictable situation. This is one of the reasons it's so important to stay in close communication with your mortgage broker, REALTOR®, lawyer, and lender. Everyone needs to understand what's happening so adjustments can be made if necessary. One issue that catches many buyers by surprise is home insurance. Most lenders require proof of insurance before they will release mortgage funds. During wildfire season, insurance companies sometimes place temporary restrictions or even stop issuing new policies altogether for homes located in high-risk areas. If you've waited until the last few days before possession to arrange your insurance, you could suddenly discover that coverage isn't immediately available. Without insurance, your lender may be unable to advance your mortgage funds, potentially delaying your closing. My advice is simple: purchase your home insurance as early as your insurer will allow. Having coverage arranged well in advance greatly reduces the chance of running into last-minute surprises if wildfire conditions change. It's one of those tasks that's easy to move to the bottom of the list until it suddenly becomes the most important item on it. Wildfires can also create a ripple effect that extends well beyond the property you're purchasing. Imagine you're buying a home in one community because your current home has sold and is scheduled to close first. Everything is carefully timed. Then a wildfire threatens your existing neighbourhood. Perhaps your buyers are unable to obtain insurance. Maybe their lender won't fund the mortgage until conditions improve. Or perhaps the buyers simply cannot complete the purchase because of evacuation orders. If the sale of your current home is delayed, you may no longer have the funds available to complete the purchase of your next home. That can create a chain reaction affecting multiple transactions, sometimes involving several families. These situations are stressful, but they also highlight why real estate professionals, lenders, and lawyers work so hard together when unexpected events occur. Everyone's goal is usually the same - to find a practical solution that allows the transaction to move forward once circumstances permit. If you're buying or selling during wildfire season, don't be afraid to ask questions. Understand how your contract addresses unforeseen events. Arrange your insurance early. Keep your financing documents up to date. Most importantly, stay in regular contact with your mortgage broker and the rest of your professional team. Wildfires are unpredictable. Preparation isn't. While none of us can control the weather, we can control how prepared we are when unexpected challenges arise. A little planning today may make all the difference tomorrow, helping ensure that when the smoke clears, you're still on track to receive the keys to your new home.
One of my favourite phone calls to make is telling a client, "Congratulations! Your mortgage has been approved." It's a huge milestone and one worth celebrating. But many buyers are surprised to learn that there are still several important steps between receiving that approval and standing in the doorway of their new home with keys in hand. The final few weeks before possession can be busy, emotional, and occasionally overwhelming. Having a plan makes the process much smoother. Stay in touch with your mortgage broker. Even after financing is approved, your broker is still working behind the scenes with your lender and your lawyer to make sure everything is ready for closing. If anything changes with your employment, income, debts, or banking before possession day, let your broker know immediately. It is always better to have a conversation early than to discover a problem at the last minute. Watch for communication from your lawyer or notary. Your lawyer will contact you to schedule your signing appointment, usually several days before your possession date. Don't wait until the last minute to book this appointment, especially during busy times of the year when legal offices are handling many transactions. Your lawyer will also provide a statement showing exactly how much money you need to bring to closing. This includes your down payment (if it hasn't already been paid), closing costs, legal fees, property tax adjustments, and other applicable expenses. Be sure to ask your lawyer what form of payment they require. Most will request a bank draft or certified funds, and you'll want to allow yourself enough time to obtain those from your financial institution. Get your down payment ready. One of the most common causes of unnecessary stress is scrambling to move funds at the last minute. If your down payment is coming from investments, an RRSP through the Home Buyers' Plan, another financial institution, or the sale of another property, make sure those funds are available well before your lawyer's deadline. Some investments require several business days to redeem, and transferring money between institutions can take longer than many people expect. Arrange your insurance. Your lender will require proof that the home is insured before they release your mortgage funds. Contact your insurance broker early so there is plenty of time to arrange coverage beginning on your possession date. Book the movers sooner rather than later. Professional movers often book weeks—or even months—in advance, particularly during the busy spring and summer moving season or at month-end. Whether you're hiring movers or borrowing your friend's pickup truck, having a moving plan in place early will save you a lot of stress. Transfer your utilities. Nothing takes the excitement out of moving day quite like discovering the electricity hasn't been connected. Arrange to transfer or activate services such as electricity, natural gas, water, internet, television, garbage collection, and any security monitoring before possession day. Some providers require advance notice, so don't leave these calls until the final week. Update your address. Changing your address is one of those jobs that's easy to forget until important mail starts arriving at your old home. Take time to update your address with: Canada Post Your employer Banks and credit card companies Insurance providers CRA Your driver's licence and vehicle registration (according to your province's requirements) Medical providers Subscription services Family and friends A simple checklist can prevent a surprising number of headaches later. Don't underestimate the emotions. Buying a home is one of the largest financial decisions most Canadians will ever make. Even when everything is going perfectly, it's completely normal to experience a wide range of emotions. Excitement. Anxiety. Second-guessing. Relief. Even a little panic. I've seen first-time buyers worry they've forgotten something important. I've seen families leaving homes where they raised children feel unexpectedly emotional. I've seen retirees excited about a fresh start while also grieving the chapter they're leaving behind. These feelings are all perfectly normal. A home purchase isn't just a financial transaction—it's a life transition. Give yourself permission to feel both excited and sentimental. Both can exist at the same time. The finish line is worth it. The days leading up to possession often feel like a whirlwind of paperwork, packing boxes, phone calls, and checklists. But before long, you'll be unlocking your front door, carrying in that first box, and beginning a brand-new chapter. As mortgage brokers, we're proud to help clients secure financing. But we're just as proud to help guide them through the entire journey—from the first conversation about affordability to the moment they finally receive the keys. After all, mortgage approval isn't the end of the process. It's the beginning of your next adventure.
Don't wait until the last minute! Learn how consistent maintenance and small upgrades can ensure a quick and profitable home sale.
If there is one question I hear more than any other from Canadians looking to buy a home, it's this: "How much can I actually afford?" It's a great question, and frankly, it's one that deserves more attention than simply finding out the maximum mortgage amount a lender is willing to approve. While mortgage qualification guidelines provide a useful starting point, they don't always tell the whole story. The amount a lender says you can borrow and the amount you can comfortably afford are often two very different numbers. Let's start with what affects affordability. One of the biggest factors is the type and amount of income you earn. A salaried employee with a stable employment history will generally have a straightforward qualification process. However, self-employed individuals, commissioned salespeople, seasonal workers, and those with multiple income sources may qualify differently. Lenders carefully examine the stability and consistency of income when determining how much mortgage financing they are willing to provide. Consumer debt is another major factor. Credit card balances, lines of credit, car loans, personal loans, and other monthly obligations all reduce purchasing power. Every dollar committed to debt payments is a dollar that cannot be allocated toward a mortgage payment. It is not uncommon for borrowers to increase their purchasing power significantly simply by reducing or eliminating high monthly debt obligations before applying for a mortgage. The size of your down payment also plays an important role. A larger down payment reduces the amount you need to borrow and often improves your overall financial position. In some cases, a larger down payment can help borrowers qualify for homes that might otherwise be out of reach. It can also lower monthly payments and reduce the total amount of interest paid over the life of the mortgage. Of course, lenders use formulas and qualification ratios to determine affordability. These calculations consider mortgage payments, property taxes, heating costs, and other obligations. However, these formulas do not always account for the realities of everyday life. That's why I often encourage clients to think beyond what they can qualify for and focus on what they can comfortably live with. A mortgage should support your life, not control it. Many Canadians are surprised to discover that once they factor in groceries, fuel, insurance, utilities, childcare, activities for children, pet expenses, travel plans, and rising day-to-day living costs, there is less room in the monthly budget than they initially expected. Homeownership also comes with unexpected expenses. Furnaces fail. Appliances break down. Roofs need repairs. Vehicles require maintenance. Life happens. If your mortgage payment consumes every available dollar each month, even a relatively small unexpected expense can create financial stress. For this reason, I often recommend that homebuyers leave some breathing room in their budget whenever possible. Choosing a home that costs slightly less than the maximum amount you qualify for can provide flexibility and peace of mind. It allows you to continue saving for retirement, build an emergency fund, take a family vacation, or simply sleep better at night knowing you have a financial cushion. Before making an offer on a home, I encourage buyers to look at the complete monthly picture. Consider not only the mortgage payment but also property taxes, home insurance, utilities, maintenance costs, and any strata or condominium fees. Then compare those costs against your current spending habits and financial goals. The goal is not simply to buy a home. The goal is to own a home comfortably while maintaining the lifestyle and financial security that matter to you and your family. The most successful homeowners are often not the ones who borrow the most money. They're the ones who make thoughtful decisions, leave room in their budget for life's surprises, and build long-term financial stability along the way. So the next time you ask, "How much can I actually afford?" remember that the answer isn't just about what the bank will approve. It's about what allows you to enjoy your home while still enjoying your life.
One of the most common misconceptions I hear from clients who are self-employed is that getting a mortgage is either impossible or requires years of perfect financial statements. Fortunately, that's simply not true. Canada's workforce has changed dramatically over the past decade. More people than ever are running their own businesses, working as contractors, driving revenue through side hustles, consulting, freelancing, or operating incorporated companies. Lenders have adapted to recognize that self-employed borrowers often have strong incomes, even if their tax returns don't tell the whole story. The key is understanding that mortgage qualification for self-employed individuals is different—not necessarily harder. Why Self-Employed Income Can Be Challenging Most traditional mortgage lenders rely heavily on income reported to the Canada Revenue Agency. The challenge is that many business owners work with accountants to legitimately reduce taxable income through business deductions and write-offs. While this strategy can lower taxes, it can also create challenges when applying for a mortgage. For example, a business owner may generate $150,000 annually but only report $80,000 in taxable income after deductions. A lender reviewing only tax returns may see a very different financial picture than the reality of the business. Fortunately, lenders have developed several solutions specifically designed for entrepreneurs and business owners. Traditional Income Verification The first option is conventional financing. Many self-employed borrowers qualify through standard programs by providing two years of Notices of Assessment, T1 Generals, business financial statements, and supporting documentation. This route typically provides access to the lowest available interest rates and is often ideal for borrowers whose reported income accurately reflects their earnings. However, when taxable income doesn't fully represent actual cash flow, alternative solutions may be more appropriate. Insured Stated Income Programs One of the most valuable tools available to self-employed Canadians is the insured stated income mortgage program. These products are available through lenders that work with mortgage insurers such as Sagen and Canada Guaranty. Under these programs, eligible self-employed borrowers can qualify based on a reasonable stated income amount that aligns with their occupation, industry, business revenues, and overall financial profile. Lenders still perform due diligence. Borrowers must demonstrate that their stated income is reasonable and supported by the business. Documents such as business licenses, GST registrations, articles of incorporation, bank statements, and proof of business activity are commonly reviewed. This program can be a game-changer for successful entrepreneurs whose tax returns don't fully reflect their true earning capacity. Generally, borrowers must have been self-employed for at least two years, maintain good credit, and provide a minimum down payment that meets insurer requirements. Business-for-Self Programs Through Alternative Lenders For some borrowers, particularly those with shorter self-employment histories or more complex income situations, alternative lenders can offer additional flexibility. These lenders often take a more holistic approach, reviewing business bank statements, retained earnings, contracts, assets, and overall financial strength rather than focusing solely on taxable income. While rates and fees may be slightly higher than traditional financing, alternative lending can provide an excellent stepping stone toward future conventional financing. The Manulife Small Business Owner Program One niche solution that has generated significant interest among self-employed Canadians is the Manulife Bank Small Business Owner Program. This program is designed specifically for incorporated business owners and can provide an alternative method of income qualification by looking beyond traditional personal income reporting. In many cases, the program considers factors such as corporate financial performance, retained earnings, and the overall health of the business. This can be particularly beneficial for incorporated entrepreneurs who intentionally leave profits within their company for growth and tax planning purposes. Programs like this recognize a reality that many business owners face: what appears on a personal tax return may not accurately represent their true financial strength. Credit Still Matters Regardless of which mortgage program is being considered, credit remains one of the most important factors. Strong credit scores demonstrate responsible financial management and can significantly improve both approval odds and financing options. Before applying for a mortgage, self-employed borrowers should ensure that payments are current, credit card balances are managed responsibly, and any errors on their credit report are addressed. Preparation Makes All the Difference The most successful self-employed mortgage applications are usually the result of preparation. Having organized financial records, current tax filings, business banking information, and supporting documentation readily available can make the approval process significantly smoother. Working with a mortgage broker can also be particularly valuable because brokers have access to a wide range of lenders, including major banks, credit unions, monoline lenders, and specialized self-employed programs that may not be available directly through a branch. The Bottom Line Being self-employed should not prevent you from achieving homeownership. Today's mortgage marketplace offers more options than ever before for entrepreneurs, contractors, consultants, tradespeople, and small business owners. From traditional income verification to insured stated income solutions and specialized programs such as Manulife's Small Business Owner Program, there are pathways available for many different situations. If you're self-employed and considering a home purchase or refinance, don't assume the answer is no. Often, the challenge isn't qualifying for a mortgage—it's simply finding the lender and program that best understands how your business operates.
When Debt Keeps You Up at Night, Your Home Equity May Offer a Way Forward As a mortgage broker, I’ve sat across the table from hundreds of Canadians carrying more stress than they let on. Sometimes it starts with a few credit cards after the holidays. Sometimes it’s a line of credit that slowly grows over time. Other times it’s unexpected life events — job loss, divorce, rising grocery bills, helping adult children, or simply trying to keep up in an increasingly expensive world. What many people don’t realize is how common this has become. There is often a quiet sense of shame attached to consumer debt. People feel embarrassed admitting they’re struggling, especially if they’ve always been financially responsible. I regularly hear clients say things like, “I never thought I’d be in this position,” or “I feel like I’ve failed.” But needing help does not mean you’ve failed. It means you’re human. One of the most effective tools available to homeowners is refinancing a mortgage to consolidate high-interest debt. By using equity in the home to pay off credit cards, personal loans, or lines of credit, many Canadians are able to dramatically lower their monthly payments and finally breathe again. The financial math is straightforward. Credit cards often carry interest rates around 20 percent or higher. Mortgage rates are typically much lower. Rolling multiple high-interest debts into one manageable mortgage payment can free up monthly cash flow and reduce financial pressure almost immediately. But the emotional impact is often even more important. I’ve watched clients physically relax during meetings once they realize there is a realistic path forward. Instead of juggling minimum payments and watching balances barely move, they regain a sense of control. They sleep better. Relationships improve. The constant anxiety starts to ease. The key, however, is timing. Too many people wait until they are already in serious financial trouble before exploring refinancing options. They drain savings, miss payments, max out credit cards, or fall behind on bills while hoping things will somehow improve on their own. Unfortunately, once credit scores begin to drop significantly, refinancing becomes more difficult and more expensive. That’s why I encourage homeowners to have the conversation early — before missed payments happen, not after. A strong credit profile gives borrowers more options, better rates, and greater flexibility. Waiting too long can limit those choices considerably. Seeking advice early is not a sign of weakness; it’s smart financial planning. It’s also important to understand that refinancing should not be viewed as a “last resort.” In many cases, it is simply strategic debt management. Business owners do it. Professionals do it. Young families do it. Retirees do it. Millions of Canadians have used the equity in their homes to simplify their finances and regain stability. Of course, refinancing is not a magic solution. It works best when paired with honest budgeting and a commitment to avoiding the same debt cycle moving forward. But for many homeowners, it can provide the reset they desperately need. If you are losing sleep over debt, know this: you are far from alone, and there are often more options available than you think. The hardest part is usually making the first phone call.