Your Mortgage Person

Tracy Head • October 5, 2023

I had a call from one of my favorite realtors a few weeks ago asking if I could help her clients. She told me that the clients had started with another broker but that things didn’t seem to be going well. I told my realtor that I would chat with her clients but would not compete with another broker – I know how much work goes into putting a file together and won’t try to undercut another professional. I did chat with the clients. Their broker had an approval in place and their closing date was less than three weeks away. They were getting extremely frustrated with the multiple requests for documents. They couldn’t understand why the broker kept coming back for more and more paperwork.


I asked a few questions about their particular situation then spelled out the list of documents I would typically ask for (specifically for their situation) upfront. They got very quiet. It was almost exactly what their broker had asked for. In fact, the other broker had also asked for all of the documents upfront. They decided they would send bits and pieces based on what they felt like providing.


The other broker had the approval in place with a great lender and had a great package for the clients. We had a discussion about why lenders ask for the documents they do, and I told them that they were actually slowing their broker down by not providing the information he needed right away.


Not entirely sure that they were happy with my thoughts but they did send the rest of the documents to their broker the same night. Their financing was signed off the following day. Problem solved. The same realtor called last week with another set of clients who were struggling with their lender. After listening to what was happening I did end up working with these clients. They had shopped for the lowest rate online and reached out to one of the well-advertised discount brokerages. They had an accepted offer on their dream home. The clock was ticking on their financing clause.


I am assuming that they ended up working with a less experienced broker at the firm. They had been told the incorrect amount for their minimum down payment, no discussion was had about closing costs, no documents had been requested, and they were told in error that they would be exempt from the property transfer tax.


A week and a half of the time they had to line up their financing had already passed. They had four days left to finalize their financing. They are an amazing young couple who have worked hard to save their down payment and get their ducks in a row. They sent me their documents within a day and we had an approval with all of the conditions signed off in two days.


Two learnings out of these situations:


  1. When your mortgage person asks for specific documents, it makes the process go much smoother for you if you send in what they’ve requested. Taking a few minutes to make sure your documents clearly show your name is important. Sending all pages of the documents key.


  2. Work with a mortgage professional. Much like most other industries there are mortgage providers with different levels of knowledge and experience, and different personalities. Working with someone from a smaller firm (as compared to a high-volume discount brokerage) often means you will have someone who is far more attentive to your needs. It is wise to do your due diligence to make sure the person you are working with knows their stuff and is a good fit with you personality-wise.

a. Longer time in the industry does not necessarily mean more knowledge or experience. Some people who are newer to the industry take ongoing learning and work with mentors to offer their clients amazing service.


Buying a home is a huge investment and commitment. It is very challenging to qualify for a mortgage

right now, so working hand-in-hand with your mortgage person will help the process go much smoother for you.

Tracy Head

Mortgage Broker

GET STARTED
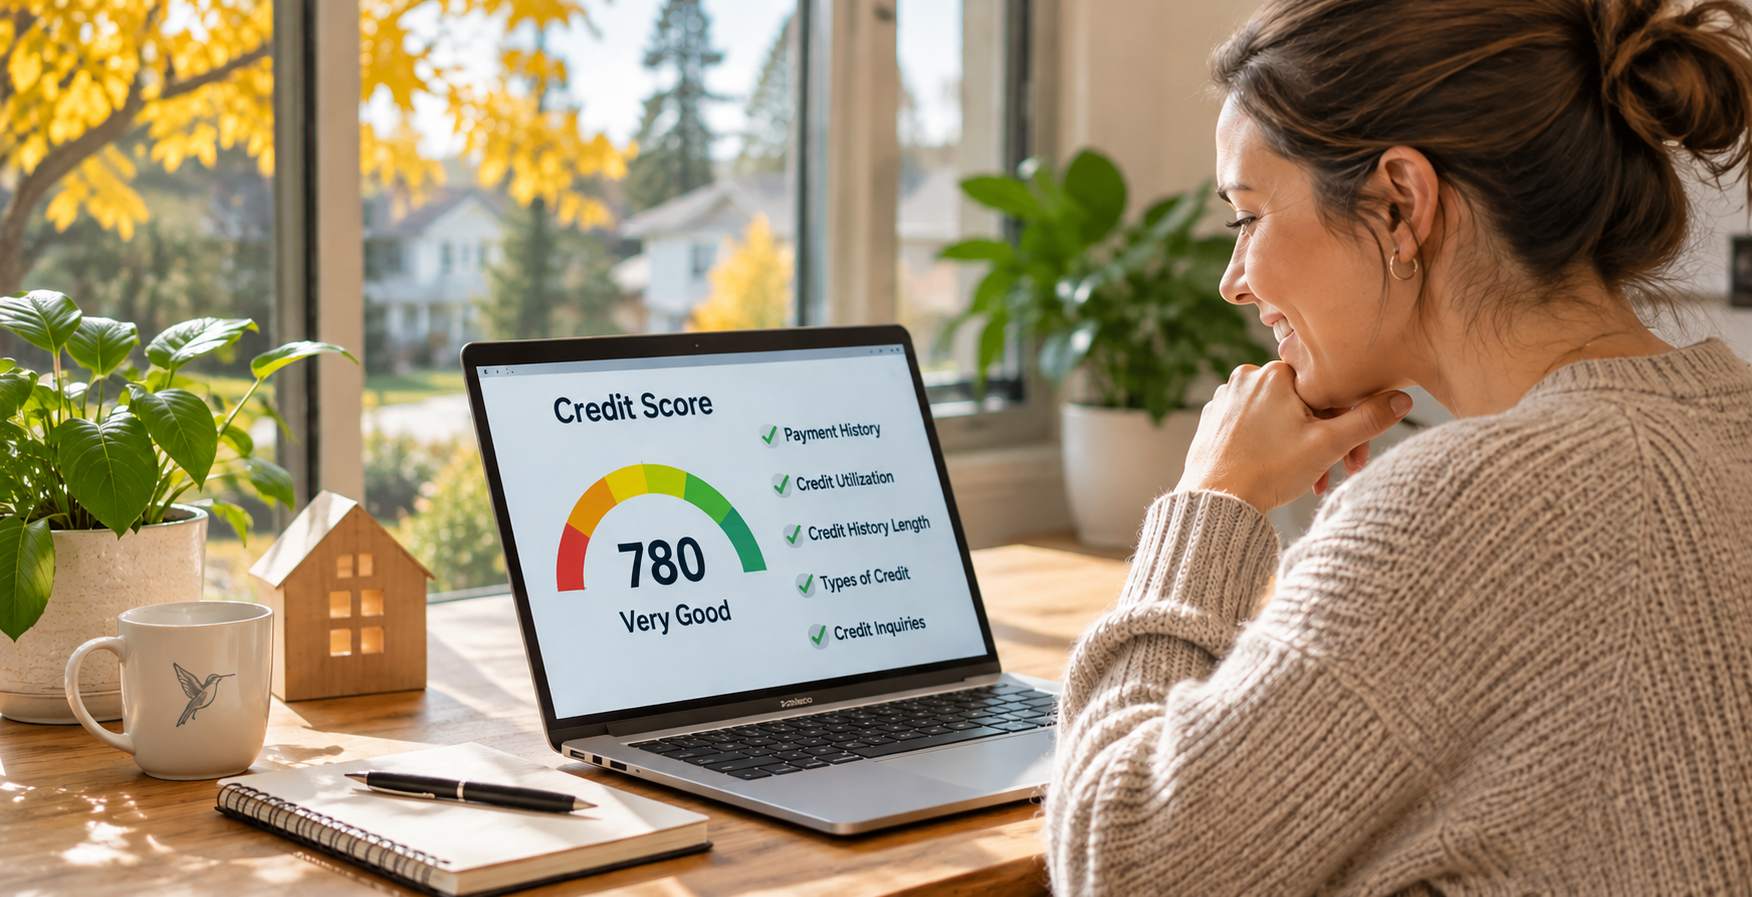
Woman working on laptop by a window, viewing a colorful dashboard with a 79% score and green bar chart
By Tracy Head • November 16, 2026
One of the conversations I have often with clients is about credit scores. Whether someone is purchasing their first home, upgrading to a larger property, refinancing, or renewing their mortgage, credit often plays a bigger role than they realize. The good news is that understanding how credit scores work can put you in a much stronger position when it comes time to apply for a mortgage. How is your credit score calculated? In Canada, credit scores generally range from 300 to 900. They are calculated using information in your credit report and are designed to predict how reliably you manage borrowed money. Lenders have their own policies about the minimum credit score they will accept. For most a score of 680 is the magic number. Several factors contribute to your score: Payment history : Consistently making payments on time demonstrates financial responsibility. Late payments, collections and missed payments can significantly hurt your score. Credit utilization : This measures how much of your available credit you are using. For example, if you have a $10,000 credit card limit and carry a $5,000 balance, your utilization is 50%. Ideally, aim to keep this below 30%, and even lower if possible. Length of credit history : The longer you've responsibly maintained credit accounts, the more history lenders have to evaluate. Types of credit : Having a reasonable mix of credit, such as credit cards, lines of credit and installment loans, can contribute positively. Credit inquiries : Frequently applying for new credit can negatively affect your score, particularly if you have a limited credit history. Something that surprises many Canadians is that we have two major credit reporting agencies: Equifax and TransUnion. Both collect information about your borrowing and repayment history, but they don't necessarily receive identical information from every creditor. They also use different scoring models. Your Equifax score and TransUnion score can be quite different, even when checked around the same time. It's also important to understand that the score you see through your bank or a credit monitoring service may not be the exact score a mortgage lender uses. Lenders can use different scoring models depending on the mortgage product and lending institution. There are several simple habits that can make a meaningful difference over time: Pay your credit card before the statement cutoff date. This is one of my favourite tips. Credit card companies commonly report balances around the statement date. If you pay down your balance before that date, a lower balance may be reported to the credit bureaus, reducing your utilization. Remember, this is separate from your payment due date. Always make at least the required payment by the due date. Keep balances below 30% of your available limits. Ideally, aim for 10% or less where practical. As you pay down credit cards or lines of credit, do not reduce the limits. Leaving the limit as it is shows you have a lower percentage of used credit. Never miss a payment. Set up automatic minimum payments or calendar reminders to avoid late payments. Before applying for another credit card, car loan or line of credit, consider whether you really need it. Multiple applications can lower your score. Keep older accounts open when appropriate. Closing an established credit card can affect your utilization and credit history. Check both credit reports regularly. Look for incorrect balances, accounts you don't recognize or reporting errors. Dispute inaccuracies with the appropriate credit bureau. Pay down outstanding debt. Reducing revolving balances can improve your utilization and strengthen your overall financial picture. Remember, credit improvement takes time. There is no overnight fix, but consistent habits can produce meaningful results. Here's something else I explain to clients: your credit score is only one piece of the mortgage approval puzzle. When reviewing an application, lenders generally consider five important areas: Income and employment : Is your income sufficient, stable and verifiable? Salaried, hourly, commissioned and self-employed borrowers may each have different documentation requirements. Debt servicing ratios : Lenders calculate your Gross Debt Service (GDS) and Total Debt Service (TDS) ratios. These compare your housing costs and overall debt payments against your gross income. Down payment : Where is the money coming from? Lenders want to verify that your down payment and closing costs are available and come from an acceptable source. Credit history : lenders review payment patterns, outstanding balances, previous financial difficulties and how responsibly you've managed credit. The property : The property's value, condition, location and marketability can all influence the lender's decision. Lenders also consider the mortgage stress test, which helps determine whether you can afford payments at a qualifying interest rate higher than your actual contract rate. My advice is simple: don't wait until you've found your dream home to start thinking about your credit. Ideally, review your credit reports, pay down revolving balances and speak with a mortgage professional several months before purchasing. A strong mortgage application isn't just about having a high credit score. It's about demonstrating that you're financially prepared to take on a mortgage and manage it comfortably.  The more prepared you are, the more options you may have when it's time to negotiate your mortgage. And that's a great position to be in as a homebuyer.
By Tracy Head • October 28, 2026
If you are self-employed you know the drill. You work hard, take care of your customers, pay your bills and try to keep as much of your money as possible. When tax time rolls around, you sit down with your accountant and look for every legal way to lower your taxable income.  It makes sense. Why pay more tax than you have to? But there is a catch that many business owners do not think about until they are ready to buy a home. The same tax returns that help you save money can make it harder to qualify for a mortgage. I have seen this issue come up time and again with self-employed buyers. They run good businesses, have money in the bank and can easily afford the monthly mortgage payment. Yet, when a traditional lender reviews their tax returns, the income on paper may be too low to qualify. The good news is that there are options. The important thing is to understand them before you start shopping for a home. Not all mortgage lenders see income the same way. When most banks review a mortgage application, they want to see your personal tax returns, Notices of Assessment and other records. They usually focus on the income you report after business expenses, not the total amount your business brings in. For a self-employed person, that number can be misleading. Take a contractor who brings in $180,000 a year but claims business expenses that leave $65,000 in taxable income. The contractor may have plenty of cash to cover a mortgage payment, but the bank may qualify them using a much lower income figure. That does not mean the bank is wrong. It means the bank is working with the numbers it can prove. The key is knowing that traditional banks are not the only option. Some mortgage programs are designed specifically for people who own businesses and do not show their full earning power on a tax return. Option 1: Insured Stated-Income Mortgages One option worth exploring is an insured mortgage program for self-employed buyers. These programs may allow a lender to use a reasonable estimate of business income, supported by other records, instead of relying only on the income shown on personal tax returns. Despite the name, “stated income” does not mean you can pick a number out of thin air. The lender and mortgage insurer still need to see that your income makes sense for your type of business. They may look at how long you have been in business, your bank statements, business revenue, credit history and the size of your down payment. Some programs also allow certain business expenses to be added back when calculating qualifying income. The big advantage is that you may be able to get a mortgage through a traditional lender without paying the higher rates and fees that often come with alternative financing. There are limits, of course. Not every business or borrower will qualify, and the lender must follow the insurer's rules. You should also expect to provide paperwork to support your application. Still, this is often one of the first options I would investigate for a self-employed buyer who wants to keep borrowing costs down. Option 2: Alternative Lenders and Bank Statement Programs What happens when your tax returns do not work, and an insured program is not a fit? This is where alternative lenders can help. These lenders often look beyond your personal tax return and take a closer look at how money moves through your business. One approach is a bank statement program. The lender may review six to 12 months of business bank statements to see how much money comes in. It then estimates how much of that money is available to support your mortgage payment after business expenses. For example, imagine a business has $240,000 in deposits over a year. A lender might apply an expense allowance based on the type of business and use the remaining amount to estimate qualifying income. The actual calculation varies by lender, and not every dollar deposited counts as income. A lender will also want to understand where the money comes from. Transfers between accounts, borrowed funds and other deposits that do not come from business sales may not count. The advantage is simple: the lender can get a better picture of your business cash flow, even if your taxable income is low. The downside is the cost. Alternative mortgages often come with higher interest rates, lender fees and stricter rules about the down payment. Depending on the lender and your situation, you may also have fewer mortgage products to choose from. These mortgages can make sense when they help you buy a home you can comfortably afford. But they should be chosen with a plan, not simply because they are the easiest approval to get. The tax savings versus mortgage costs is where things get interesting. Most business owners want to reduce their tax bill. That is understandable, and there is nothing wrong with claiming legitimate business expenses. The problem comes when tax savings today create a bigger financing cost tomorrow. But here is something many self-employed buyers overlook: paying more income tax just to qualify for a traditional mortgage is not always the best financial move. Let's say you save several thousand dollars in income tax by claiming legitimate business expenses. A year or two later, you want to buy a home, but your reported income is too low to qualify with a regular bank. You may now need an alternative mortgage with a slightly higher rate and an upfront lender fee. At first, that might sound like a bad deal. But when you compare the actual costs, it may be the better option. Consider a $600,000 mortgage. If an alternative lender charges an interest rate just one percentage point higher than a traditional lender, the difference would be about $6,000 in interest over a year if the full balance stayed at $600,000. In practice, the difference will change as you make payments and your mortgage balance declines. Now compare that cost with the extra income tax you might pay by reporting a higher taxable income. Depending on your business expenses, tax bracket and province, the additional tax bill could be substantial. You could end up paying more in taxes than you would have spent on the higher mortgage rate and lender fees. Of course, you need to run the numbers carefully. Alternative mortgages can come with lender fees, legal costs and penalties if you refinance too soon. The rate difference may also change over time, and there is no guarantee that you will qualify for a traditional mortgage later. The point is that paying more tax is not automatically cheaper than paying a little more for your mortgage. In some cases, keeping your legitimate business deductions and using an alternative lender can leave you in a stronger financial position. The best approach is to compare both options before making a decision. Ask your accountant to estimate the extra tax you would pay if you reported more income. Then ask your mortgage broker to calculate the full cost of an alternative mortgage, including interest, fees and any expected refinancing costs. You may find that paying a modest premium for your mortgage is a better deal than giving up valuable tax deductions. The goal is not to avoid taxes at all costs, nor is it to qualify for a mortgage at any cost. It is to look at the whole picture and choose the option that leaves more money in your pocket over time. If buying a home is on your radar in the next one to three years, it is worth having a conversation with both your accountant and a mortgage broker before making major decisions about how you report your income. Ask your accountant to explain the tax savings from your current approach. Then ask a mortgage broker to estimate what you could qualify for under different lending options. You may discover that a traditional mortgage is still within reach. Some lenders can make reasonable adjustments for certain business expenses, and insured self-employed programs may offer more flexibility than you expect. If those options do not work, a bank statement mortgage may be a sensible short-term solution. In that case, ask what it would take to move to a lower-cost mortgage later. That could mean building a stronger income history, improving credit, paying down debt or waiting until your tax returns better support the mortgage you need. Most importantly, do not wait until you have found your dream home to start figuring this out. The bottom line is that being self-employed should not mean you have to pay more for a mortgage than necessary. But the way you manage your business finances can affect the choices available to you when it is time to buy a home. Saving tax is important. So is keeping your financing costs under control. The goal is not to pay the most tax or the least tax. It is to make informed decisions that work for your business today and your plans for tomorrow. A little planning can make a big difference. And when it comes to buying a home, knowing your options before you need them is one of the smartest moves a business owner can make. Important note: Mortgage programs, insurer rules, rates and fees change from time to time. This column is for general information, not personal tax or mortgage advice. Confirm current program requirements with your licensed mortgage professional and discuss tax decisions with your accountant.